

NetBenefits - Fidelity at Work

- 7.83K Reviews
- 4.0
- Downloads
- 1,000,000+
Our take on NetBenefits - Fidelity at Work from Appgk
When I look at a finance app, I care less about flashy charts and more about whether it helps me make careful decisions around money that may affect my future. NetBenefits - Fidelity at Work is built for that narrower purpose: managing Fidelity workplace accounts from a phone. The developer is Fidelity Investments, and the app is free to use, with an Everyone age rating. That makes it easy to try, but the real question is whether it fits the way you manage employer-linked benefits.
My first impression is that this is not meant to replace a general banking app or serve as a complete investing platform for every financial need. Its focus is workplace accounts. That distinction matters because the app is most useful when I want to check retirement-related information, review activity, or handle an account task connected to employment rather than move money around a normal checking account.
The app has been available since April 24, 2013, and its current version is 4.35.2. On Android, it requires at least Android 12. I see that as a practical consideration rather than a minor footnote: anyone using an older phone may need to update the operating system before deciding whether this is a convenient option.
What kind of trust does a workplace finance app need?
NetBenefits - Fidelity at Work operates in a sensitive part of my financial life. A workplace account can involve retirement savings, employer contributions, investment choices, beneficiary decisions, and personal employment information. Even when I am only checking a balance, I am opening an app that sits close to long-term financial planning. That makes account access and user control more important than visual polish.
Best Parts of NetBenefits - Fidelity at Work
Things to Keep in Mind About NetBenefits - Fidelity at Work
I also think the app deserves to be judged differently from a budgeting tool. A budgeting app may be something I open to categorize everyday spending. A workplace benefits app is more likely to be used for occasional, high-consequence decisions. I may open it after changing jobs, receiving a pay increase, reviewing a benefits message, or wondering whether my contribution is still appropriate. Those moments call for clarity and patience, not an endless stream of notifications or pressure to act.
The app’s audience is substantial: it has passed one million installs and has an average rating of 4.0 from about twenty-five thousand ratings. Those figures suggest that it is an established choice for many people, but they do not tell me whether every employer setup feels equally complete. Workplace benefits can vary by plan, employer, and account type, so I would treat the app as a secure access point to my available Fidelity workplace services rather than assume every user sees the same tools.
News and Features Related to NetBenefits - Fidelity at Work

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
That is one of the most important practical expectations to set. If my employer does not offer a particular Fidelity workplace account or feature, I should not expect installing the app to create it. The experience is shaped by the accounts connected to my employment benefits. For me, that makes it especially useful after enrollment or during a job transition, when having one place to inspect the relevant account information can reduce uncertainty.
Access and account controls deserve the most attention
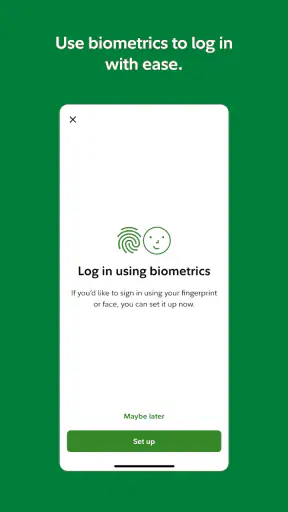
Before I use any finance app, I want to understand what happens at sign-in and what choices I have once I am inside. With NetBenefits, I would begin by checking that I am using the official app associated with Fidelity Investments, then sign in carefully rather than treating the process as casual. A workplace account is not the place to reuse an easy password or leave an unlocked phone unattended.
Don't want to read the full review?
I would also make a habit of reviewing the account after any important employment event. For example, if I changed employers, I would check which workplace accounts still appear, whether recent activity is visible, and whether the information matches what I expect from payroll or plan communications. This is a more useful test than simply opening the app once and deciding that it looks familiar.
One subtle strength of a dedicated workplace app is separation. My retirement or employer benefit information does not have to be mixed into a general-purpose banking dashboard filled with card purchases and household bills. That narrower context can make it easier to focus on long-term accounts. The trade-off is that I may need another app or website for ordinary banking, spending analysis, or broader portfolio research.
Screenshots
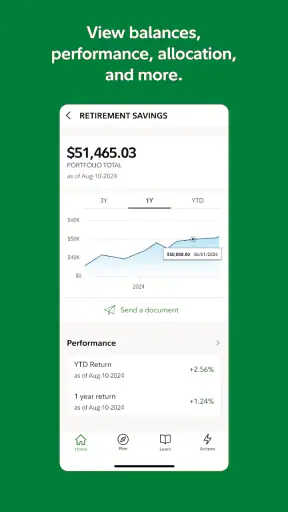
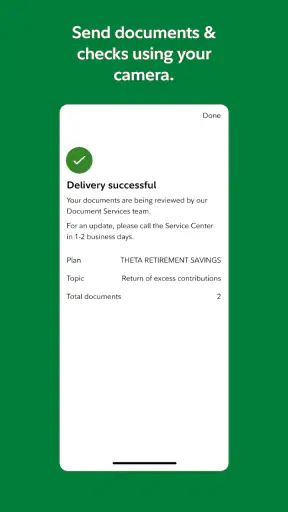
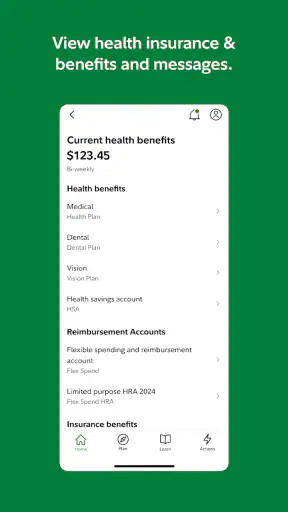
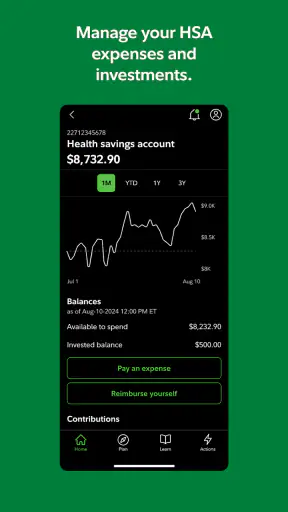
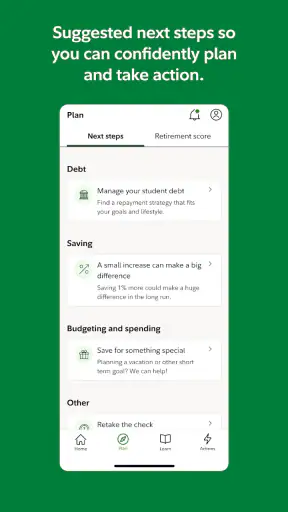
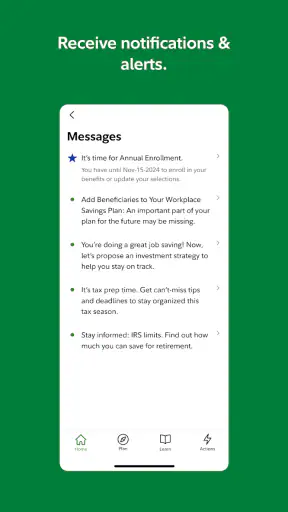
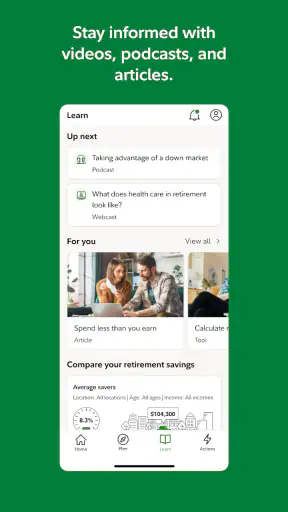
I would not use the app as a substitute for reading plan documents. A mobile screen can make an account feel simple, but contribution rules, withdrawal consequences, investment risks, and employer-specific conditions can be more complicated than a balance page suggests. My preferred workflow would be to use the app for access and monitoring, then slow down and consult the relevant plan information before making an irreversible change.
Everyday scenarios where it earns its place
Imagine I am leaving work for the day and remember that I have not checked my workplace retirement contribution since a salary change. Instead of waiting until I am at a computer, I can open the app, review the account information available to me, and decide whether I need to investigate further. The value is not that the phone makes the decision for me; it is that it lowers the effort required to notice when something deserves attention.
Another realistic situation is preparing for a conversation with human resources. If I am unsure which workplace account is connected to my employer, I can first inspect what is visible in NetBenefits and write down the questions that remain. That helps me avoid calling with a vague concern. I can ask about a specific account, transaction, or plan detail instead of trying to reconstruct everything from memory.
I also find mobile access useful for routine observation. I might check after a payroll change to see whether the expected contribution appears once the relevant activity is available. That does not replace checking a pay statement, but comparing the two can help me catch a misunderstanding earlier. The important habit is to compare sources rather than assume that a mobile balance alone proves every payroll detail is correct.
A further use case is simply reducing avoidance. Long-term savings are easy to ignore when access feels inconvenient. Having a dedicated app can make a short review more realistic, especially for someone who rarely uses a desktop. Still, I would set a personal rule not to make rushed investment changes while distracted or on a small screen. Convenience should encourage awareness, not impulsive action.
Where the app may feel limited
The focused design can also be a limitation. If I want a complete view of cash flow, credit cards, bills, taxes, and investments across several providers, NetBenefits is unlikely to be the only tool I need. A broader financial dashboard may be better for household planning, while a dedicated investment research platform may offer more depth for comparing securities and constructing a portfolio.
It may also be the wrong choice for someone who has no Fidelity workplace relationship. The app’s purpose is tied to employer accounts, so a person looking only for a general retirement calculator, a basic savings tracker, or a standalone brokerage experience should look at an option designed for that job. Installing it simply because it is free would not make it relevant.
Another source of friction is that mobile convenience can expose the difference between simple viewing and complicated account administration. A quick balance check is naturally suited to a phone. A beneficiary review, rollover decision, or investment allocation change deserves more careful reading. If the screen leaves me uncertain about an important action, I would switch to a larger device or contact the appropriate support channel rather than guessing.
The Android requirement is another practical filter. Since the app needs Android 12 or later, people keeping an older device may face a choice between updating the phone’s operating system and using another access method. I would check compatibility before relying on the app for an urgent workplace task.
Data-sensitive moments and responsible habits
Financial privacy is not only about what an app can technically access. It is also about when I choose to open it, where I use it, and how I protect the account afterward. I would avoid signing in while connected to an unfamiliar public network, especially if I am reviewing sensitive workplace information. I would also avoid taking screenshots of account pages unless I have a clear reason and a safe place to store them.
Shared devices require extra care. If I use a tablet or phone that another person can unlock, I would treat the app as sensitive even if I only plan to check a balance. I would sign out when appropriate, keep the device protected, and make sure saved credentials or notifications do not reveal more than I intend. These are user-controlled choices that matter just as much as the app’s interface.
I would pay particular attention after receiving an unexpected message related to my account. Rather than following a link from an email or text, I would open the app directly and inspect the account there. If the message claims that urgent action is required, I would slow down. Workplace finance accounts are exactly the kind of service where urgency can make people overlook basic security checks.
Notifications can be useful, but I prefer to decide how much financial information appears on my lock screen. A notification that exposes an account detail may be harmless on a private phone and uncomfortable on a shared one. My advice is to review notification behavior during setup and adjust it to the way the device is actually used, not the way I wish it were used.
How much control does the user really have?
For me, user agency means being able to inspect information without feeling pushed into a decision. NetBenefits makes the most sense when I use it as a review tool: I check what is happening, compare it with payroll or plan documents, and choose the next step deliberately. That approach is healthier than opening a financial app only when I feel anxious and then making a change simply to feel finished.
I would create a small personal checklist for important reviews. First, I would confirm that I am looking at the correct workplace account. Next, I would note the date of the information I am viewing, because account activity may not appear at the exact moment a payroll event occurs. Then I would compare the details with my records. Finally, I would pause before submitting any change that affects contributions, investments, or beneficiaries.
That checklist is useful because mobile interfaces can make a complicated action look short. A few taps may lead to a meaningful financial consequence. I do not consider fewer steps automatically better. The best experience is one that gives me enough context to understand what I am changing and enough opportunity to stop if the details do not look right.
I also appreciate the distinction between access and advice. The app can be a practical place to see my Fidelity workplace information, but I remain responsible for deciding whether a contribution level or investment choice suits my circumstances. Someone who wants personalized financial planning should not assume that a convenient account screen provides that service. In that situation, a qualified adviser or the plan’s educational material may be a better complement.
How it compares with the usual alternatives
Compared with a general banking app, NetBenefits is more specialized and less useful for everyday spending. I would not expect it to replace checking-account alerts, bill payment, or a household budget. Its advantage is concentration: workplace account information is kept in a context that is easier to revisit when I am thinking about employment benefits and long-term savings.
Compared with a desktop browser, the phone app offers more immediate access, but the smaller screen can make detailed review less comfortable. I would choose the app for quick checks and routine awareness. I would choose a browser or larger screen when I need to compare documents, study unfamiliar plan information, or carefully review a major change.
Compared with a broad investment app, NetBenefits is better suited to people whose main need is their Fidelity workplace relationship. A broader platform may be preferable for someone managing accounts from several institutions or researching investments independently. The right choice depends less on which interface looks better and more on whether the service matches the account I actually need to manage.
That comparison also explains why the app can receive mixed reactions without being a poor product. A person expecting a full personal-finance command center may find it narrow. A person who wants convenient access to an employer-linked Fidelity account may find that narrowness reassuring. I would judge it by the second use case, because that is where its purpose is clearest.
My cautious verdict for different users
I would recommend NetBenefits - Fidelity at Work to someone who has Fidelity workplace accounts and wants a straightforward mobile way to stay aware of them. It is especially worthwhile for people who tend to postpone account checks because desktop access feels inconvenient. The free price removes a common barrier, and the Everyone rating makes it broadly accessible from an age-classification perspective.
I would be more cautious about recommending it as a person’s only finance app. It is not the tool I would choose for a complete household budget, all-in-one account aggregation, or detailed investment research across unrelated providers. I would also avoid relying on it alone for decisions that require careful interpretation of plan rules.
My final view is that trust here comes from disciplined use rather than blind convenience. I would keep the device secure, open the app directly instead of following unexpected links, compare important information with payroll or plan records, and pause before confirming major changes. Used that way, NetBenefits - Fidelity at Work is a sensible companion for workplace account management: focused, established, and useful for staying engaged without pretending that a phone screen can replace thoughtful financial planning.
NetBenefits - Fidelity at Work FAQ
What is NetBenefits – Fidelity at Work used for?
NetBenefits – Fidelity at Work is designed to help eligible employees manage workplace benefits through Fidelity. After signing in, you can typically review retirement accounts, check balances and contributions, explore investment options, view transaction history, and access plan documents. The exact tools available depend on your employer’s benefits package and the Fidelity plans connected to your account.
Can I use NetBenefits if my employer does not use Fidelity?
Generally, NetBenefits is intended for employees whose employer offers a workplace retirement or benefit plan administered by Fidelity. If your company uses another provider, you may not be able to access its plan through the app. Availability can also vary by country, employer, and plan type, so checking with your human resources department or Fidelity is recommended before downloading.
How do I sign in to the NetBenefits app?
You normally sign in with your Fidelity username and password, or with the credentials provided when your workplace account was created. New users may need to complete registration, identity verification, and security setup before viewing account information. If you forget your login details, the app generally provides recovery options, although some account issues may require contacting Fidelity support.
Is NetBenefits – Fidelity at Work safe for viewing financial information?
The app is built for accessing sensitive workplace and retirement-account information, so it uses account authentication and security features intended to protect your data. You should still use the latest app version, avoid signing in on unsecured public networks, enable available biometric or multifactor security options, and never share your password or verification codes. Always download it from an official app store.
Can I make changes to my retirement plan from the app?
Depending on your employer’s plan rules and the features enabled for your account, NetBenefits may let you adjust contribution rates, review or change investment elections, manage certain account preferences, and access planning tools. Not every action is available for every plan, and some changes may require additional verification or confirmation. Review all details carefully before submitting financial or investment instructions.












